
A construction loan is not one loan. It is a staged facility, and its drawdown schedule shapes everything: what your builder gets paid, when a valuation is ordered, and why your repayments look small before jumping at completion. This tutorial walks through the mechanics in plain terms. You will learn why a construction loan is not a single lump sum, then follow the drawdown schedule stage by stage: deposit, base and slab; frame; lock-up; fixing or fit-out; and completion and final payment. We will explain who orders the progress valuation and who pays for it, how the progress payment rhythm works, and how interest-only repayments during the build compare with the repayment jump once the home is finished. You will also see two of the most expensive things that can go wrong, the questions to ask before you sign, and what a construction loan calculator does not tell you. By the end, you should understand how to align builder milestones with lender inspections and avoid a settlement blow-up. Rightfinancial has a presence in the Northern Beaches and Sutherland Shire and a self-employed specialism.
Why a Construction Loan Is Not One Loan
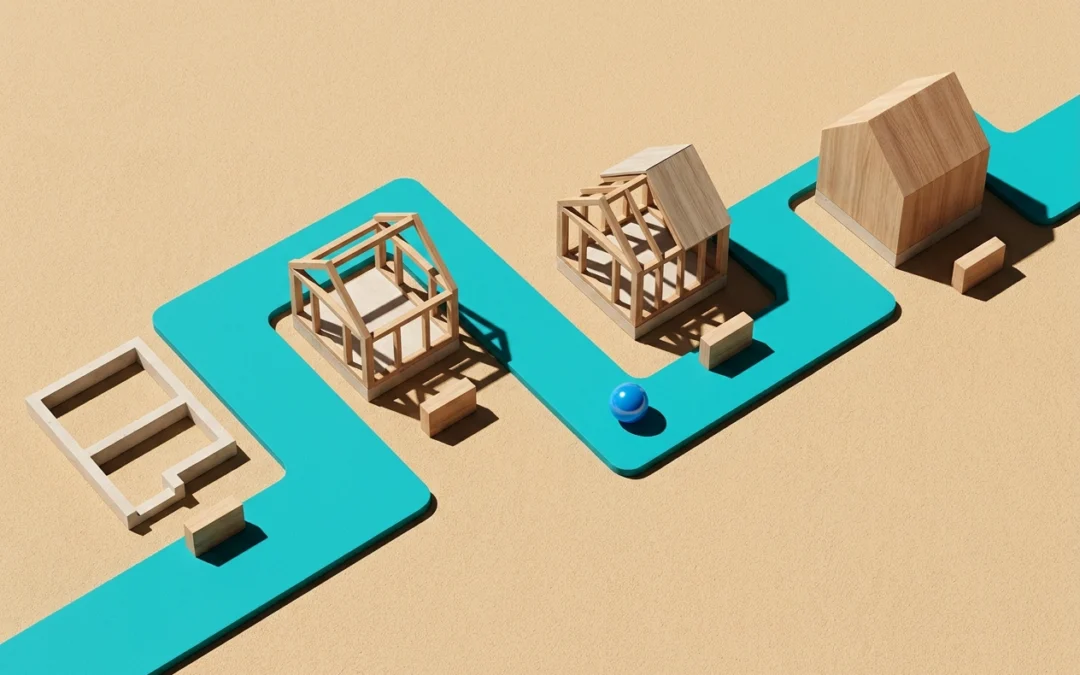
A construction loan is a staged facility, not one loan. The lender approves a total limit, then releases funds in progress payments as the build advances, so the balance climbs only as work is completed.
You do not receive the full amount at settlement. The land or existing property usually secures the facility, and the rest sits undrawn until each stage is verified and approved. Interest is generally charged only on the drawn amount, not the full limit, so early repayments look small.
It behaves differently at each stage: the balance grows, the lender’s exposure grows, and once fully drawn the structure can shift. Every construction building loan or construction home loan works this way. Rightfinancial arranges construction loans and other home loan types across the Northern Beaches from Balgowlah and Dee Why, and the Sutherland Shire from Miranda, including self-employed borrowers whose income verification differs.
The Drawdown Schedule, Stage by Stage
Most lenders structure drawdowns around recognisable build milestones: deposit and base or slab, frame, lock-up, fixing or fit-out, and completion. Treat that five-stage model as common practice, not a universal rule: lenders differ on naming, on whether base and slab are separate draws, and on how many draws a build allows.
Each draw needs evidence before release: typically a builder’s claim or invoice plus a progress inspection or valuation ordered by the lender confirming the work is done.
Percentages sit in your loan schedule and broadly track the value of work completed rather than splitting the limit evenly.
Your builder’s contract is the other half. Different stage names, different percentages or a cost-plus arrangement means the schedule will not line up with what the builder invoices.
Read the schedule before you sign the build contract, not after. A mismatch is the most common source of friction during a build.
Stage 1: Deposit, Base and Slab
Now the mechanics of the first release. The opening draw is typically available at settlement and covers the builder’s deposit, site works and the slab or base. Some lenders split it in two: deposit first, then slab.
Treat this draw as the one most likely to absorb surprises. Site costs, retaining walls, rock excavation and council or statutory charges often land here rather than being spread across the build.
Funds are released against verified work, not a calendar date. A valuer or inspector generally must confirm the slab is poured and the site is prepared before the second portion is released.
Because interest-only repayments are charged on a relatively small drawn balance at this point, your first statements can look surprisingly cheap next to the figure you were quoted.
Stage 2: Frame
Once the slab is verified, the frame draw follows, covering the structural frame, roof trusses and the start of the roof. It is a large release, because framing is a substantial share of build cost.
Lenders generally will not release frame money for a partially completed frame; the inspection must confirm the stage is finished to the contract standard, not merely underway.
This is where a builder’s claim and a lender’s inspection first diverge expensively. If the inspector returns the stage as incomplete, the builder waits, the schedule slips, and you may be asked to fund the shortfall to keep trades on site.
Ask your builder how soon after framing the claim will be submitted, and whether the frame inspection can be booked in advance to reduce the lag.
Stage 3: Lock-Up
Where frame can be held back, lock-up is judged as one package. Lock-up means the home is enclosed and watertight: external walls, roofing, windows, external doors and cladding all in place. It typically sits around the halfway mark of both the build and the drawdown schedule.
Because it is a major milestone, the inspection tends to be thorough. One incomplete item, a missing window or an unfinished roof section, can hold the entire draw rather than a portion of it.
Lock-up draws commonly trigger a review of the total limit against actual spend. If costs have drifted, expect the lender to request updated figures or contract variations before releasing further funds.
Stage 4: Fixing or Fit-Out
Past lock-up, the build moves indoors. The fixing stage is the internal fit-out: plasterboard and cornices, cabinetry and benchtops, tiling, electrical and plumbing fit-off, and often painting and floor coverings.
This is the stage most often claimed slightly early, because many small trades work simultaneously and their finishing dates overlap.
The lender’s inspector assesses the stage as a whole. If cabinetry is installed but tiling and painting are not, the draw may be reduced or withheld until outstanding items are completed.
Track your variations in writing at this stage. Selections upgrades, appliance changes and added landscaping often sit outside the fixed contract price and are not covered by the drawdown schedule. Resolve any dispute here, because the final draw depends on it.
Stage 5: Completion and Final Payment
Once fixing is signed off, the final draw follows practical completion. That usually means the occupation certificate or final building approval is issued and the lender’s final inspection confirms the works are done. A small retention is commonly held back until defects are rectified or a defects liability period begins, depending on your contract and lender.
The loan typically converts from interest-only to principal and interest here. Your repayment is then calculated on the full drawn limit, not the partial balance you paid during construction.
Do not treat the final draw as the finish line. Before the first principal and interest payment falls due, obtain the final valuation, the closing loan balance and the new repayment schedule in writing.
Who Orders the Progress Valuation, and Who Pays for It
The lender ordered that final inspection, and every earlier one. For a loan for building construction, the lender typically appoints a valuer from its own approved panel; you don’t choose or instruct them.
The report answers the lender’s question: does the work justify releasing funds? You usually get a copy, but it isn’t written for you, which matters when a stage is assessed as incomplete.
The trigger is normally the builder’s claim or invoice, or the lender’s scheduled inspection cycle, not your request. The builder’s paperwork timing drives everything.
Inspection fees are usually borrower-paid: upfront, at settlement, or deducted from the drawdown. Ask how many inspections are included and what an extra or failed one costs.
Going direct to a bank means one valuation policy, one inspection panel, one drawdown rhythm, and nobody between the builder and the credit team when a stage is disputed.
The Progress Payment Rhythm: When the Builder Actually Gets Paid
Once the inspection clears, the money has to move. In most lender models the sequence runs: the builder completes the stage and issues a claim, you sign and authorise it, the lender orders and receives the progress inspection, then the draw is paid once approved.
Builders are generally paid for certified completed work, not work in progress or materials sitting off site. That protects you, but places timing risk on the builder, which is why stage disputes escalate quickly.
Inspection booking times, approval authority limits and internal processing sit between claim and payment. Raise this lag with your builder before the contract is signed; terms expecting payment within a week of invoicing will frustrate a lender’s inspection cycle.
Keep a running record of every claim, inspection outcome and payment date. If the build runs long or a stage is disputed, that record is what you and your broker work from.
Interest-Only During the Build, and the Repayment Jump at Completion
Released draws are typically interest-only during the build, and interest accrues only on the drawn balance. Draw $150,000 of a $600,000 limit and you pay interest on $150,000 alone.
Illustrative arithmetic only: $600,000 at 6% interest-only with $150,000 drawn is about $750 a month. On the full $600,000 over 30 years at principal and interest, it is roughly $3,600. Your rate, term and drawn amount decide the real figures.
That jump is construction lending’s most predictable shock, and avoidable. Budget from day one on the finished balance. Interest-only periods are usually capped at a set number of months. Ask what happens if the build overruns, because the loan can convert to principal and interest while trades are on site
Two of the Most Expensive Things That Go Wrong
A builder claims a stage complete. The lender’s inspector disagrees. The draw is withheld or reduced, trades slow, and you fund a gap you never planned for. Agree the stage definitions in writing with both parties before work starts.
The completion repayment shock is the second: twelve months of interest-only figures, then principal and interest on the full limit. Stress-test the finished repayment at the start.
Cost overruns sit behind both. Variations, upgrades and site conditions outside the fixed price often leave the final draw short of the final invoice, and a completion valuation below contract price can reduce the lender’s final position further.
Building a first home? Confirm which first home buyer schemes in NSW you can use. Self-employed borrowers should also get their income documentation in order early.
Not necessarily the most common failures, but among the most expensive and most foreseeable.
Questions to Ask Before You Sign
Both problems above are cheaper to prevent than to fix, and prevention starts with five questions at the signing table.
- Do the construction loan’s stage names and percentages match my builder’s contract exactly? Put both documents side by side.
- Who pays for progress inspections, how many are included, and what does a failed inspection cost me?
- How long is the interest-only period, what happens if the build overruns it, and what is the principal and interest repayment on the full approved limit?
- If the builder’s claim and the lender’s inspection disagree, what is the process, and who represents me in that conversation?
- If I’m self-employed, how does the lender want income evidenced at each draw, and what needs updating mid-build?
Rightfinancial works with self-employed borrowers on that last question regularly. Get every answer in writing before work starts.
What a Construction Loan Calculator Does Not Tell You
Those questions set the structure; the calculator only sets a starting point. A standard construction loan calculator estimates a repayment on one loan amount and one rate. A staged facility never has a single balance for most of the build, so it cannot model the drawdown schedule, interest-only on a rising drawn balance, a held-back retention, or the conversion to principal and interest on the full limit at completion.
To approximate the build period, run interest-only on the average drawn balance across the stages. Then calculate principal and interest on the full approved limit separately. That second number is the one your budget needs to survive.
For self-employed borrowers, the income assumptions are the least reliable part, and lenders may want updated figures at drawdown.
The Bottom Line on Construction Loans
A calculator is a starting point; the decision rests on two budgets. Price the build, then the principal and interest repayment on the full approved limit after completion. Get both right before you sign anything.
Before work starts, confirm your loan’s drawdown stages, your builder’s contract stages and the lender’s inspection definitions all describe the same milestones. Keep every claim, inspection result and payment in one file.
Budget from day one on that finished repayment, and know the cost if the build runs past interest-only.
Building on the Northern Beaches or in the Sutherland Shire? Right Financial, a mortgage broker Northern Beaches clients rely on, including self-employed borrowers, can walk you through the drawdown schedule and valuation process before you commit. Book a conversation with the Balgowlah, Dee Why or Miranda team.
Conclusion
A construction loan is really a sequence of loans released as the build progresses. Three takeaways: your builder’s contract stages, the lender’s drawdown schedule and its valuation definitions must describe the same milestones before work starts; the builder is paid on a progress rhythm, not a steady drip; and interest-only ends with a repayment jump calculated on the full approved limit.
So budget from day one for that finished principal and interest figure, not the smaller drawn balance, and keep every claim, inspection and payment in one file. A calculator is a starting point, never the plan.
Going straight to a bank often means applying one lender’s rules in isolation, with less support at drawdown time. If you are building on the Northern Beaches or in the Sutherland Shire, Right Financial’s Balgowlah, Dee Why and Miranda team can walk you through the drawdown schedule before you commit. Book that conversation and sign with confidence.
Frequently Asked Questions
Why isn't a construction loan a single lump sum?
A construction loan is a staged facility. The lender approves a total limit and releases funds in progress payments as the build advances, so the balance only climbs as work is completed. The undrawn portion sits unused until each stage is verified and approved.
What are the stages in a typical drawdown schedule?
Most lenders structure drawdowns around five common build milestones: deposit and base or slab, frame, lock-up, fixing or fit-out, and completion with final payment. The post treats this as common practice rather than a universal rule, since lenders differ on naming, on whether base and slab are separate draws, and on how many draws a build allows.
What does a lender need before releasing a progress payment?
Each draw needs evidence before release: typically a builder's claim or invoice plus a progress inspection or valuation ordered by the lender confirming the work is done. Builders are generally paid for certified completed work, not work in progress or materials sitting off site.
Who orders and pays for the progress valuation?
The lender orders the progress inspections and typically appoints a valuer from its own approved panel, so the borrower does not choose or instruct them. Inspection fees are usually borrower-paid, either upfront, at settlement, or deducted from the drawdown. The post advises asking how many inspections are included and what an extra or failed one costs.
Why are repayments small during the build and then jump at completion?
Interest-only repayments are charged only on the drawn balance, so early repayments look small. At completion the loan typically converts from interest-only to principal and interest, calculated on the full drawn limit rather than the partial balance. The post's illustration: $600,000 at 6% interest-only with $150,000 drawn is about $750 a month, while principal and interest on the full $600,000 over 30 years is roughly $3,600. These are illustrative figures only.